How Small Businesses Can Create a Practical Risk Management Plan
Risk is part of running any company, but small businesses often have fewer resources available to absorb disruption. A delayed supplier, equipment failure, cyber incident, cash flow problem, or unexpected staff absence can quickly affect daily operations. A practical risk management plan helps owners identify potential threats, understand their likely consequences, and prepare realistic responses before a problem occurs. It does not need to be complicated. The most useful plan is clear, focused, and easy to apply when pressure is high.
Understand the Purpose of Risk Management
Risk management is not about predicting every possible event or removing uncertainty from the business. Its purpose is to help decision-makers recognize significant risks, reduce avoidable exposure, and respond consistently when disruption happens.
For a small business, this means concentrating on the events that could interrupt essential operations, harm customer relationships, create financial pressure, or damage important systems and assets. The plan should reflect how the business actually works rather than relying on generic templates that may overlook its specific priorities.
Identify the Risks That Matter Most
Begin by examining the business from several perspectives. Consider what could prevent the company from delivering products or services, collecting revenue, supporting customers, or meeting important obligations. Speak with employees who manage day-to-day processes, as they may recognize weaknesses that are not immediately visible to the owner.
Common areas to review include:
- Operational risks: Equipment breakdowns, process failures, quality issues, or the loss of access to premises.
- Financial risks: Cash flow pressure, late customer payments, unexpected costs, or dependence on a small number of clients.
- Technology risks: Cyberattacks, data loss, software outages, weak access controls, or unreliable backups.
- People risks: Staff shortages, loss of specialist knowledge, workplace incidents, or unclear responsibilities.
- Supplier risks: Delayed deliveries, price changes, product shortages, or overreliance on one provider.
- Reputational risks: Customer complaints, service failures, misleading communications, or poor handling of sensitive information.
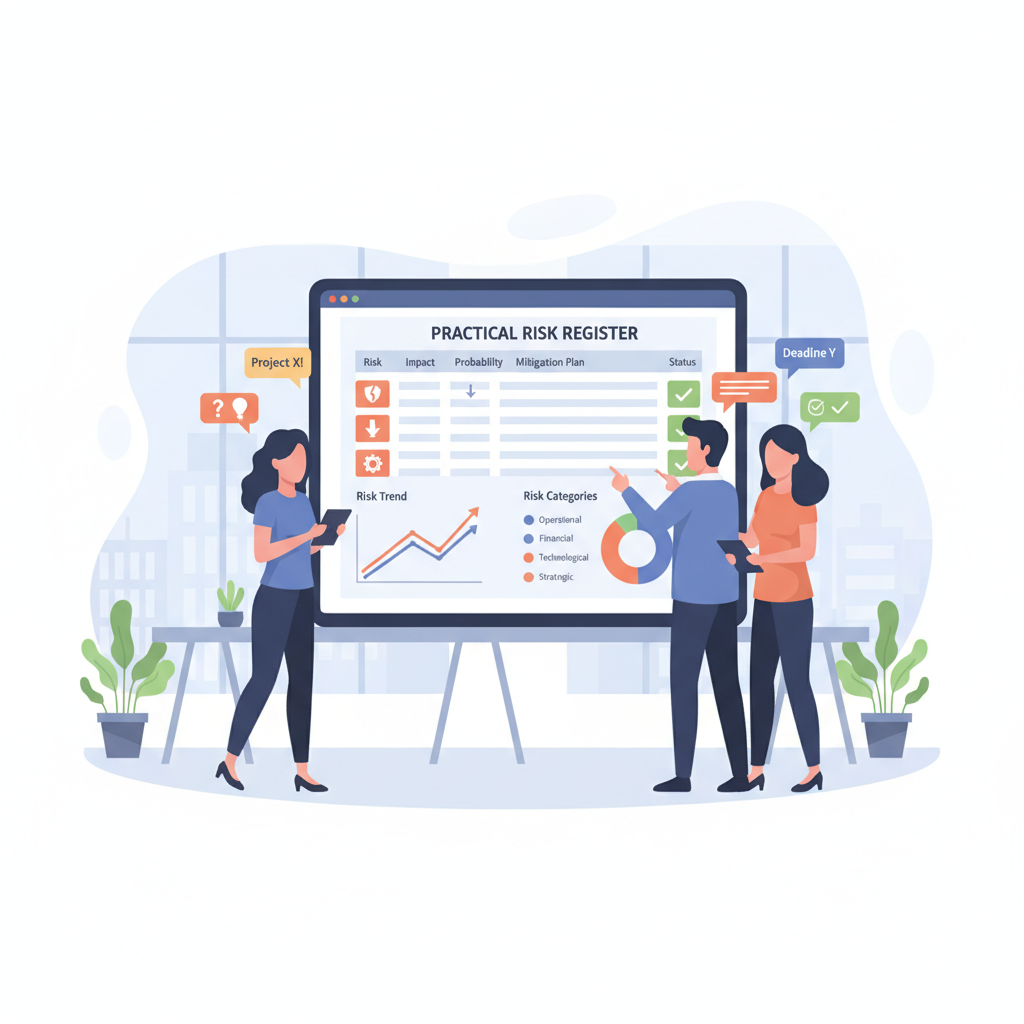
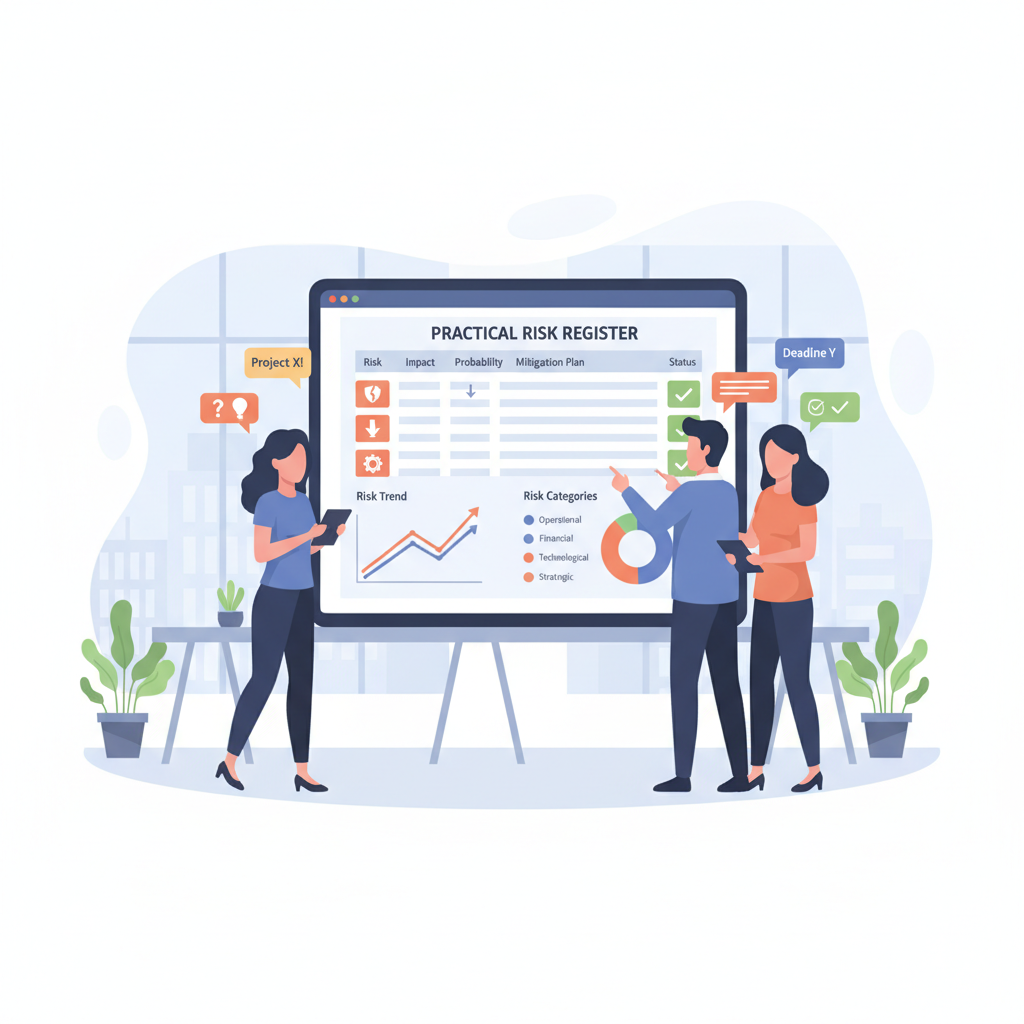
Keep the initial risk register manageable. A shorter list of meaningful risks is more useful than a long document filled with unlikely scenarios.
Assess Likelihood and Potential Impact
Once risks have been identified, evaluate how likely each one is to occur and how seriously it could affect the business. A simple rating of low, medium, or high is often sufficient. The aim is not to produce a perfect forecast, but to create a sensible order of priority.
Consider the effect on revenue, customer service, employees, operations, technology, and reputation. Also think about how quickly the impact would appear. A temporary delay may be manageable, while the loss of a critical system could require immediate action.
Risks with both a high likelihood and a serious potential impact should receive attention first. Low-priority risks can still be recorded, but they should not distract from issues that could threaten business continuity.
Prepare Practical Risk Responses
Each priority risk should have a realistic response. The business may choose to reduce the likelihood of the event, limit its impact, transfer part of the exposure, or accept the risk while monitoring it. The right approach depends on available resources and the importance of the affected activity.
Use Clear Preventive Controls
Preventive actions should be specific and achievable. Examples include maintaining equipment, reviewing user access, training employees, backing up essential data, documenting key processes, and identifying alternative suppliers. Controls should have a named owner so that responsibility does not become unclear.
Create Response Procedures
Document what should happen if the risk becomes a real incident. Include the first actions to take, who has authority to make decisions, which employees need to be informed, and how customers or suppliers will be contacted. Store essential contact details somewhere accessible even if normal systems are unavailable.
Where legal, financial, insurance, or compliance questions arise, small business owners should consider seeking guidance from an appropriately qualified professional rather than treating the risk plan as a substitute for specialist advice.
Protect Business Continuity
A risk management plan should support the continued delivery of the company’s most important products and services. Identify the activities that cannot remain unavailable for long, along with the people, systems, information, equipment, and suppliers they depend on.
Practical continuity measures may include:
- Keeping secure backups of essential business information.
- Documenting critical tasks so another employee can perform them.
- Maintaining current emergency and supplier contact details.
- Preparing alternative working arrangements where appropriate.
- Identifying replacement suppliers or service providers.
- Creating clear internal and customer communication templates.
These preparations should be proportionate to the business. Small companies do not need elaborate crisis structures, but they do need clear responsibilities and workable alternatives.
Record Ownership and Warning Signs
Every major risk should be assigned to a person who can monitor it and coordinate the response. The risk owner does not need to solve every problem personally, but should understand the controls, recognize warning signs, and know when to escalate an issue.
Warning signs might include increasing payment delays, repeated system errors, declining supplier performance, unusual account activity, or growing dependence on a single employee. Monitoring these indicators can help the business act before a developing problem becomes a serious interruption.
Review and Test the Plan Regularly
A risk management plan becomes less useful when it is created once and then forgotten. Review it at regular intervals and whenever the business changes significantly. New technology, employees, premises, suppliers, services, or customer contracts can introduce risks that were not previously relevant.
Testing is equally important. Discuss a realistic disruption with the team and walk through the planned response. Check whether contact information is current, backups can be accessed, employees understand their roles, and alternative arrangements are workable. Use any weaknesses discovered during the exercise to improve the plan.
Keep Risk Management Practical
The strongest small business risk management plan is not necessarily the longest. It is the one that identifies genuine priorities, assigns clear responsibilities, and provides actions people can follow. By reviewing business risks, assessing their impact, preparing proportionate responses, and protecting critical operations, owners can make their companies better prepared for uncertainty.
Risk management should remain part of normal business decision-making rather than a separate administrative task. When the plan is simple, current, and understood by the team, it becomes a practical tool for protecting continuity and supporting confident growth.